Why Belgium makes its living from other people's goods
1 911 words · 9 min · updated 2026-09-10
 Back to Belgium
Belgium imports raw materials and semi-finished goods, processes them and re-exports them, which is what a small country at the mouth of the Rhine delta does for a living when the motorways and the railways of northern Europe run through it. Output was 725.5 billion United States dollars in 2025, or 60,750 dollars a head, with exports equivalent to over two thirds of gross national income.
In short
- Gross domestic product
- 725.5 billion USD in 2025
- Per head
- 60,750 USD in 2025
- Growth
- 1% in 2025
- Gini coefficient
- 26.8 in 2023
- Exports
- over two thirds of gross national income
- Diamond exports
- roughly a tenth of Belgian exports
- Primary deficit
- 3.4% of output in 2025
- Wage indexation
- automatic, tied to a consumer price index
What the economy produces
The 2025 figure was 725.5 billion United States dollars of output, which is 60,750 dollars a head, or 74,676 dollars at purchasing power parity. Growth was 1%, inflation 2.5% and unemployment 5.9%. Income is distributed unusually evenly, at a Gini coefficient of 26.8 in 2023.
The description is a highly developed high-income mixed economy, and its advantages are stated the same way in every account of it: a central geographic location, a well-developed transport network, a diversified industrial and commercial base, and a highly skilled, multilingual and productive workforce.
| Figure | Value | As of |
|---|---|---|
| Gross domestic product | 725.5 billion USD | 2025 |
| Per head | 60,750 USD | 2025 |
| Per head at purchasing power parity | 74,676 USD | 2025 |
| Growth | 1% | 2025 |
| Inflation | 2.5% | 2025 |
| Unemployment | 5.9% | 2025 |
| Gini coefficient | 26.8 | 2023 |
| Exports | over two thirds of gross national income | recent |
What a transit economy actually does
Exports are equivalent to over two thirds of Belgian gross national income, which is a level of trade dependence few countries reach, and the composition explains why. Belgium imports raw materials and semi-finished goods, processes them further, and re-exports them. Apart from coal, which is no longer worked, the country has almost no natural resources of its own, which means every input has to be bought and every advantage has to be manufactured.
That model requires infrastructure rather than endowments, and Belgium built it. The port of Antwerp handles cargo on a European scale, its freight railway station accounts for a third of all Belgian freight traffic, and the motorway and rail networks connecting the ports to the Rhine, the Ruhr and northern France are among the densest anywhere.
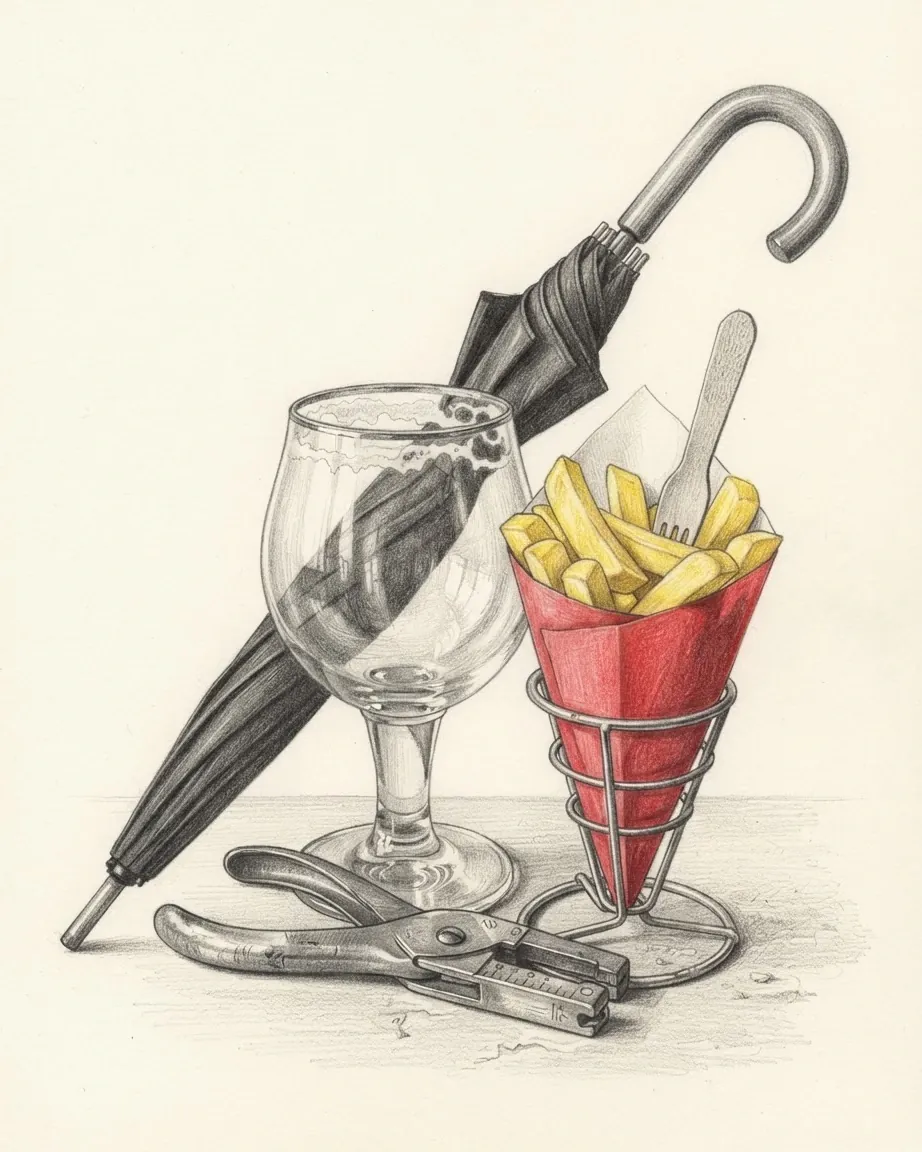
Antwerp is also the world's leading diamond market, and diamond exports account for roughly a tenth of Belgian exports. That single trade is a good illustration of the whole model: stones are neither mined nor consumed in Belgium, and the value added lies in cutting, grading, financing and trading them. The business depends on trust, expertise and a concentration of dealers in a few streets rather than on any physical advantage, and it has stayed in one city for centuries for exactly that reason.
Chemicals are the industrial expression of the same logic. The Antwerp-based BASF plant is the largest of its kind outside Germany, petrochemicals developed on the back of foreign investment in the 1960s and 1970s in which United States firms played a leading role, and the sector converts imported feedstock into exported product.
Where the industry sits
Belgian industry is concentrated in Flanders in the north, around Brussels, and in the two largest Walloon cities, Liège and Charleroi, along the corridor known as the Sillon industriel.
That corridor is where the country's economic history happened. Belgium was the first European country to join the industrial revolution in the early nineteenth century, and it did so along the coal seam running east to west through Wallonia. Coal, steel, glass and heavy engineering made the francophone south the wealthy half of the country for a century.
The reversal is the defining economic fact of modern Belgium. Coal closed, steel contracted, and the industries that replaced them located in Flanders, on the ports and the motorways rather than on a seam. Output per head, employment rates and investment have favoured the north for decades, and the political settlement described in the politics article is largely an attempt to manage that divergence.
Foreign investment shaped both halves. It contributed substantially to growth in the 1960s and it means a considerable share of Belgian industry answers to headquarters elsewhere, which is the standard condition of a small open economy and a real constraint on national industrial policy. A government negotiating with a plant whose investment decisions are taken in another country has fewer instruments than one dealing with a domestic owner, and Belgium has spent decades competing for those decisions through tax and infrastructure rather than through ownership.
What the outlook is
The OECD projects growth falling to 0.7% in 2026 before picking up to 1.1% in 2027. Energy support measures and partial wage indexation only partly offset the effect of inflation and fiscal consolidation on purchasing power, which weighs on consumption, and headline inflation is projected to rise to 3.5% in 2026 before slowing to 2.6% in 2027.
The recent pattern has been unsteady. Growth slowed sharply at the end of 2025 on weaker external demand and softer household spending, then picked up from 0.2 to 0.8% annualised in the first quarter of 2026. Business investment proved resilient through 2025 while housing investment kept falling, reaching 16% below its 2019 level, which in a country with a large owner-occupied housing stock and high household wealth is a signal about interest rates rather than about incomes, and consumer confidence fell to its lowest point since April 2025 while business confidence and export orders stayed weak.
The named risk is energy. The energy shock and geopolitical tensions drag on exports, and the OECD states plainly that potential gas or oil shortages pose a risk for a Belgian industry that is highly dependent on fossil fuel. A transit and processing economy built on imported feedstock is exposed to fuel prices twice: once in what it buys and once in what it costs to move.
Where the work is
Unemployment at 5.9% in 2025 is moderate by European standards and conceals a wide regional spread, with rates in Brussels and parts of Wallonia running well above those in Flanders. A national figure in a country this divided describes an average nobody actually experiences, and Belgian labour market policy is designed around the regional spread rather than around the headline.
The employment rate rather than the unemployment rate is the number Belgian policy argues about. A comparatively large share of the working-age population is neither employed nor counted as unemployed, sitting instead on early retirement, disability or long-term sickness, which is why the consolidation measures name incentives to reduce long-term sickness absence and a higher effective retirement age alongside a cap on unemployment benefits.
Language is a labour market factor in a way it is almost nowhere else. A workforce described in every account as highly skilled and multilingual is an asset for the international sector in Brussels, and the requirement to work in Dutch, French or both is a genuine barrier to mobility between regions for people who have one of them.
Labour costs are high and productivity is high with them, which is the standard position of a northern European economy. The competitiveness argument in Belgium is therefore not about the level of wages in isolation but about how quickly they move relative to the neighbours, which is the indexation question again from the employer's side.
What the country runs on for energy
Belgian industry is highly dependent on fossil fuel, which the OECD names as a specific risk in the event of gas or oil shortages, and the country has almost no domestic production of either.
The electricity system has been shaped by a long argument about nuclear power. Belgium built a substantial nuclear fleet, legislated a phase-out, and has repeatedly amended the timetable as security of supply and climate targets pulled in the opposite direction from the original decision, which leaves the country planning its power system around a policy that has changed more than once.
The alternatives are constrained by geography. A small, flat, densely populated country has limited room for onshore wind and limited hydropower, so offshore wind in the North Sea has carried most of the renewable build-out, and the sea area available for it is finite and shared with the shipping lanes that serve the ports of the Rhine delta and carry a great deal of northern Europe's cargo.
Interconnection is therefore the strategy as much as generation, and Belgium has built more of it relative to its size than most European countries. Belgium sits between France, Germany, the Netherlands and Britain and trades electricity across all four borders, which turns a national supply problem into a regional one and makes Belgian energy security partly a function of decisions taken in other capitals.
What wage indexation does
Belgium is one of very few European countries that still operates automatic wage indexation, under which wages rise with a measured index of consumer prices without a negotiation taking place.
The effect during an inflation shock is to protect purchasing power quickly and to raise labour costs at the same time. The OECD's assessment notes partial indexation among the measures that mitigate the impact of inflation on households, and the corresponding argument, made by employers and by international institutions repeatedly, is that automatic indexation erodes competitiveness against neighbours whose wages adjust more slowly.
The system survives because it is genuinely popular and because removing it would require agreement between social partners and across the language divide. Successive governments have adjusted its mechanics, excluded particular items from the index and suspended it temporarily, rather than abolishing it. The most common adjustment has been to the basket the index is measured against, which changes the outcome without touching the principle, and that is a characteristically Belgian way to resolve a dispute: alter the technical parameter and leave the political question where it was.
Whether it is a strength or a weakness depends on the shock. In an inflation episode driven by imported energy, indexation transmits an external cost shock into domestic wages and prices; in a period of stable prices it does very little at all.
What the state costs and owes
Fiscal consolidation is set to begin in 2026, following a widening of the primary deficit to 3.4% of output in 2025, with a structural primary balance improvement of around 0.5% of potential output expected in each of 2026 and 2027.
The measures named are on both sides of the ledger. On labour supply: a cap on unemployment benefits, stronger incentives to reduce long-term sickness absence, and a further increase in the effective retirement age. On revenue: shifting household excise duties from electricity to fossil fuels, and higher securities and bank taxes.
Two of those are worth noticing for what they say about the country. Long-term sickness absence has become a large enough item to appear in a macroeconomic consolidation plan, and moving excise duty off electricity and onto fossil fuels is a tax change designed to make electrification cheaper rather than a revenue measure dressed as one.
The structural difficulty is the same one the politics article describes. Consolidation has to be agreed between a federal government that holds the debt and social security, and federated entities that hold much of the spending, and no Belgian budget is settled without a negotiation between levels as well as between parties. A consolidation plan that the federal government can announce but the regions deliver is a plan whose execution depends on six governments agreeing, which is the same constraint that makes forming one of them take so long. Belgium: politics works through the machinery that has to reach it.
Common questions
Questions about Belgium
How big is the Belgian economy?
725.5 billion United States dollars of output in 2025, which is 60,750 dollars a head, or 74,676 dollars at purchasing power parity. Income is distributed unusually evenly, at a Gini coefficient of 26.8 in 2023.
Where do Belgian exports go?
Largely goods it imported first. Belgium brings in raw materials and semi-finished goods, processes them and re-exports them, with chemicals, pharmaceuticals, vehicles, food products and diamonds among the main categories. Diamond exports alone account for roughly a tenth of the total, and exports overall are equivalent to over two thirds of gross national income.
Where does the gap between Wallonia and Flanders come from?
Because the industries reversed. Belgium was the first European country to industrialise in the early nineteenth century, along the coal seam running through Wallonia, and when coal and steel declined the replacement industries located in Flanders on the ports and motorways instead. Output per head and employment have favoured the north for decades.
What is Belgian wage indexation?
A system in which wages rise automatically with a measured consumer price index rather than through negotiation. It protects purchasing power quickly during an inflation shock and raises labour costs at the same time, and it is one of very few such systems left in Europe.